Just because property values have improved this past year, still does not necessarily mean that your assessed value is where it should be. Between July 2 and September 16, Orange County property owners who believe that their homes have been valued too high for property tax purposes can request a formal review of their property tax assessment value for the upcoming 2013 tax bill.
To do this you need to complete, print out, and sign the Clerk of the Board's Online Application for Changed Assessment, which is available at https://assessmentappeals.ocgov.com/aa/ you must mail the signed form to the Clerk before the deadline.
This is only for your base property tax rate and has nothing to do with special assessments. While on the topic of special assessments - remember this year when you file your tax return, you can no longer write off the special assessments as a part of your property tax bill on your California State Income Tax Form. Although legitimately we were never to write off the special assessments, it went without any enforcement until 2012 when the State has decided to enforce that component and you can be liable for fines and back unpaid taxes if you continue to use things such as your Mello Roos assessment as a property tax deduction.
Wednesday, August 28, 2013


Sunday, August 4, 2013
Interest Rates and Inventory...What To Do???
Well, as interest rates slowly creep back up so is our inventory. While by most recent standards rates are higher (A/O 6/27/13 4.46%) we want to remember those lows of 11/2012 when they hit 3.31%. But back in November we had very little inventory and very little activity outside of the "all-cash buyer". But, many of you remember the days back in 1981 when rates skyrocketed to 18.63%. Although that was an unusual high - hovering in the 6-8% range has occured for the first decade of this century. Yes, as rates creep up your buying power shrinks...so now is the time to go looking. Inventory in Orange County, CA as of 7/3/2013 was up to 4,727 units. The low end of the market is shrinking while the upper ends continue to show growth. The largest sector of the market locally that has grown is the properties in the $500K to $750K price range which has increased 74% since March of this year. With the increase in inventory we will see a less crazy, more normal housing market which is really what we want and need.
What I hear many people saying is that we are in a new "housing bubble". While housing prices are not going to go crashing down anytime soon, as more sellers add to the inventory, the housing market is becoming more balanced and appreciation will slow down. Higher interest rates will also encourage that balance.
What I hear many people saying is that we are in a new "housing bubble". While housing prices are not going to go crashing down anytime soon, as more sellers add to the inventory, the housing market is becoming more balanced and appreciation will slow down. Higher interest rates will also encourage that balance.
Wednesday, July 31, 2013
More Information About Purchasing Again After A Short Sale - It's All About How It Is Reported
Current Fannie Mae guidelines require a 2 year waiting period after a borrower has had a short sale to be eligible for new financing with a 20% down payment. The loan must be submitted through Fannie Mae’s automated underwriting system, Desktop Underwriter (DU), to insure the short sale on their credit report will be approved.
There are three different results DU will report a loan file as:
A) Approved/Eligible-this means the buyer is approved
B) Refer/Eligible-this means the buyer’s file must be manually approved by an underwriter
C) Refer with Caution- this is a loan denial
There are 3 main credit bureaus that collect and report the information-Experian, Equifax and TransUnion. Each of the bureaus makes their own decision on what internal codes are to be used in reporting a short sale. The code most commonly used is an I-5, “Installment with Severe Delinquency”. Unfortunately the code I-9 is sometimes reported which represents a “Foreclosure”.
If two of the bureaus report an I-5 and one of the bureaus report the short sale as an I-9, Desktop Underwriter reads the report as a foreclosure and will issue a Refer with Caution because the waiting period after a foreclosure with FNMA is 7 years.
Experian refuses to change the code from I-9 to I-5 if they are the bureau reporting the short sale as a foreclosure. Their reasoning is the definition of a short sale is a pre-foreclosure which is deemed a type of foreclosure.
The remedy would be a manual underwrite because the buyer’s documentation would prove the home sold and the bank settled for less than full. However, most investors require a DU Approve/Eligible in order for them to purchase the loan so most lenders do not offer a manual underwrite on Fannie Mae loans.
One solution has been waiting for the 3 year time period to elapse and finance with FHA. The waiting period after a foreclosure is 3 years with FHA. The down side is the mortgage insurance requirement even if the borrower has 20% down payment. That can be a very expensive option for the buyer.
The takeaway from this is to know it is more than just meeting the timeframe after a short sale for the buyer to be eligible for new financing. The buyer needs to be fully approved by having their loan file entered in Fannie Mae’s automated underwriting system and have the final decision be Approved/Eligible before entering escrow.
Wednesday, July 3, 2013
Mello-Roos Explained
In 1978 California voters passed Proposition 13 which limited property taxes to about 1% of assessed value. This was great for homeowners but didn't resolve the issue of local communities needing access to tax revenues to support schools and infrastructure in newer communities. In 1982 as an end-run around Proposition 13, state legislators came up with the Community Facilities Act or more commonly referred to as Mello-Roos (named after the bill's sponsors). Mello-Roos is a special assessment on real property and is commonly found in the newer developments of Orange County, CA. Mello-Roos tax assessments help fund schools, new roads, and infrastructure such as water bonds, bridge bonds, etc. It is an assessment based upon either square footage of the lot or the building and runs usually from 15 to 30 years. Since the assessment is based upon bonds that are floated, the re-financing of these bonds can extend the initial time period of the assessment.
As a Realtor, many people specifically state that they do not want to pay Mello-Roos taxes, so you need to steer clear of areas such as Talega, Coto de Caza, Ladera Ranch, Newport Coast, and most of Aliso Viejo. Although there are newer developments such as the Reserve in San Clemente that do not have Mello-Roos taxes specifically because the developer paid off the bonds and wrapped those fees into the actual price of the homes. In Talega, the initial development had two Mello-Roos bonds while the "newer" part has an additional bond to cover the cost of the bridges. While in the age-restricted senior community, they only pay one bond (water), since to pay for a school bond would not be fair to retired homeowners.
Everyone plugged along using the Mello-Roos tax assessment as a write-off on their income tax returns along with all the other "special" assessments that show up on property tax bills. That is until NOW! Effective in the 2013 tax year, ALL special assessments can no longer be written off as a tax deduction on income tax returns. This is causing many homeowners additional grief since there are so few tax write-offs to begin with. Many homeowners in Mello-Roos tax districts are re-evaluating the cost of these assessments.
One idea that I am attempting to apply is paying off the Mello-Roos assessment at the close of escrow in selling a home. Once the assessment is paid off, the home remains free and clear of Mello-Roos for the remainder of it's life. Many homeowners are not even aware that this is an option, and it really needs to be used more frequently as a market differentiation strategy. So in essence you can buy in Talega without the burden of Mello-Roos taxes (if you happen to negotiate with a seller that is open to this strategy).
With tighter lending, eliminating the Mello-Roos cost could allow you to afford more house and who wouldn't rather have more house than more taxes?
Wednesday, June 12, 2013
PHOTOS FROM NEW LISTING
 |
| Street view of house from street |
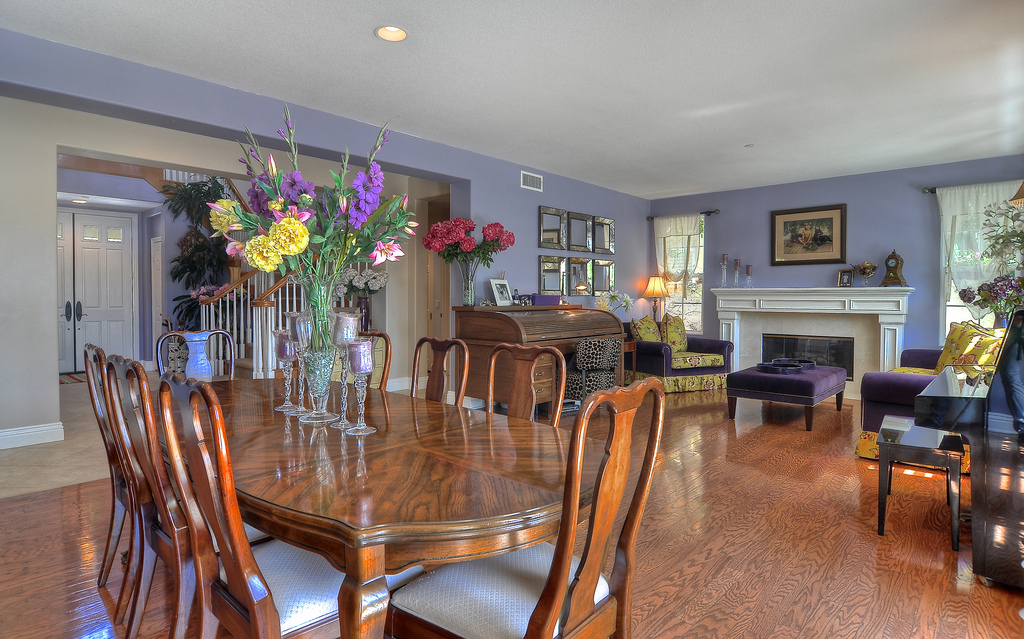 |
| Dining room into living room with peek of entry in rear |
 |
| Family room toward eat in kitchen |
 |
| Master bedroom |
 |
| Master bathroom |
 |
| Rear patio area |
THE BEST OF TALEGA WITHOUT THE BURDEN OF MELLO ROOS
Enjoy the best of Talega without the burden of Mello Roos taxes. Picture yourself in this recently updated light and private 6 bedroom, 5.5 bath home that has two downstairs bedrooms both with in-situ baths. From this ideal end of cul-de-sac location, the property boasts a large wrap around rear and side yard including a black pebble-tec saltwater rock pool, spa, waterfalls and a large entertaining area with built-in Jenn-Air gas grill.
Updated kitchen (May 2012) with stainless steel Kitchen Aide appliances including a built-in French door refrigerator, slab Colonial Cream granite, large center island, and a walk-in pantry. Master bath was updated last summer with slab Carrara White Italian Marble. Large porcelain oval handmade vessel sinks by Whitehaus with Kraus fixtures. Tub surround with slab marble and Calcutta gold marble tile backsplash. Tub and shower were designed with access panels to plumbing valves.
Handpainted crown molding in the master bedroom with a bult-in bookshelf unit. The powder room was updated with granite, a glass vessel sink with waterfall faucet and a "statement" mirror. Two additional bathrooms were updated this year with Venetian Marble. The upstairs Jack 'n Jill bath in Blanco Perlato, Kohler under-mount sinks with glass tile backspash and decorative accents in the tub/shower with frameless European shower door. The downstairs bath was done in Tibetan Beige with a Kohler under-mount sink with glass and metal tile backsplash and decorative accents in the stall shower with a frameless shower door.
The side yard was designed with copper pipe custom-made arbors which is a haven for the local hummingbirds and finches while a small producing veetable garden is in the side rear. There is room for children's play equipment or a trampoline. Pacifica is easy walking distance to the Talega Swim and Athletic Club and the private Calle Altea Park. This property has a three-across direct access garage with 7'9" garage doors for higher profile vehicles with a large driveway that can easily accommodate 4 additional cars.
This is NOT your typical Talega home, but so much more...call for a private viewing

Monday, January 28, 2013
Update on Getting A Mortgage After Bankruptcy or Foreclosure
As with most things these days, the rules seem to change as our real estate market struggles to improve. It used to be that if you suffered a bankruptcy or foreclosure you could kiss home ownership goodbye for at least 7 years, now for the most part, the rules say that you must wait at least 3 years, depending upon the reason you lost your house.
If you lost your house do to "extenuating circumstances" over which you had no control; this includes "life-changing" events such as a job loss, serious illness, or the death of a wage earner. A divorce, a business failure or being overwhelmed by too much credit does not count. You won't just automatically qualify, but you must provide documentation that you can handle credit and afford the payments. You need a squeaky clean credit history after your life changing event.
Unfortunately, after the loss of a home, many people cut up the credit cards and live on cash. That won't cut it, you must show a good payment history to obtain a mortgage. Although you can develop an alternative credit report using your rent payments, utility bills, and cellphone payments, most lenders still want to see trade lines and a credit score.
The other factor that comes into play is if you seek a mortgage with a government-backed financing, the wait time is usually less. For instance, mortgages insured by the Department of Veterans Affairs, after a Chapter 13 bankruptcy, the minimum wait time for VA financing is just 12 months; a Chapter 7 bankruptcy the wait is usually about 24 months.
FHA has essentially the same rules as the VA regarding bankruptcies - one year for Chapter 13 and two years for Chapter 7. If you went through a short sale or foreclosure it is usually three years...again if there are documentable extenuating circumstances the waits can be shorter.
For conventional loans, the wait times are tiered, 2 years after a short sale if there are extenuating circumstances, 4 years without. Freddie Mac guidelines say that when a borrower's financial issues were due to his mismanagment: An acceptable credit reputation must be reestablished for at least 84 months if he or she was foreclosed upon, 60 months if the borrower filed more than one bankruptcy petition in the last seven years, 48 months after the discharge or dismissal of a Chapter 7 bankruptcy, and 48 months after conveyance of a deed in lieu of foreclosure or a short payoff.
The wait is 48 months for all other significant adverse or derogatory credit information, but only 24 months from the discharge date of a Chapter 13 bankruptcy. If extenuating circumstances can be shown, and if there is evidence on the credit report that the borrower has reestablished an acceptable credit reputation, the wait is 36 months if you went through a foreclosure of filed more than one bankruptcy petition in the last seven years. If the bankruptcy was discharged or dismissed, the wait is only 24 months. As well as for a short sale, deed-in-lieu, or if the borrower suffered another significant adverse or derogatory credit event.
So don't despair, there is light on the horizon.
Tuesday, December 11, 2012
Some Great Charts To Check Out
The following post has some great charts regarding the real estate market and when they are anticipating will be the best time to sell...like wait until 2019...but the BEST time to buy is right NOW!!!
Tuesday, November 6, 2012
Update on Some Recent California Real Estate Laws
The California Bill of Rights was enacted into law on July 11, 2012 to assist struggling Californians keep their homes. This law will go into effect on January 1, 2013 and it aims to avoid foreclosure where possible. It generally prohibits lenders from engaging in dual tracking, requires a single point of contact for borrowers seeking foreclosure prevention alternatives, providers borrowers with certain safeguards during the foreclosure process, and provides borrowers with the right to sue lenders for material violations of this law. The bulk of the law applies to first trust deeds secured by owner-occupied properties with one-to-four residential units.
Another new law is California Education Code section 48204 which extends until 2017 a school district's ability to admit a student if the student's parent works at least part-time within the boundaries of that school district.
Another new law is California Education Code section 48204 which extends until 2017 a school district's ability to admit a student if the student's parent works at least part-time within the boundaries of that school district.
Monday, November 5, 2012
A Story About Buying Again After Foreclosure
November 02, 2012 12:07 am • Pete Carey - San Jose Mercury News
LIVERMORE, Calif. -- R.C. and Stacy Davis lost their condominium to foreclosure in 2009, a bad break that seemed destined to keep them from buying another home for many years.
Yet last week (only three years after their foreclosure) the couple signed the papers to buy a four-bedroom house.
Their avenue to homeownership? A loan backed by the Federal Housing Administration.
"We're as happy as can be," Stacy Davis said.
The ability to get an FHA loan so quickly after a foreclosure could be welcome news to thousands of people who lost their homes during the housing bust.
While mortgage giants Fannie Mae and Freddie Mac make people wait seven years after a foreclosure, the FHA will approve loans after three years, providing the buyer has established good credit and the ability to pay the mortgage.
"There's definitely a movement of folks who have had a foreclosure to re-emerge and re-engage in the market," said Dustin Hobbs of the California Mortgage Bankers Association. He said brokers have picked up on the trend.
"It helps the housing market," said Guy Schwartz of CMG Financial, which handled the Davises' mortgage.
The FHA, which is self-supporting, provides mortgage insurance for loans with low down payments and more flexible household income requirements. The Davis loan came with a 3.5 percent down payment plus required monthly mortgage insurance and a 3.75 percent interest rate on a 30-year loan.
"An FHA loan is a good option for those who can qualify," said Paul Leonard, California director of the Center for Responsible Lending. And there couldn't be a better time to try, he said.
"We are at near substantial price corrections," he noted. That and low interest rates present "kind of a historic opportunity if people can qualify," he said.
But it's not clear whether there's a flood or a trickle of new borrowers with foreclosures in their recent past.
The FHA said it doesn't have data on how many of the loans it insures involve people who are buying homes after a foreclosure or short sale.
Wells Fargo, the country's largest FHA loan originator and servicer, said it doesn't break out those loans. In the first six months of this year, Wells Fargo has made more than $73 billion in FHA-backed loans compared with $47 billion last year, spokesman Jim Hines said.
Mason McDuffie Mortgage in San Ramon is working with foreclosure victims.
"We are making loans and have made loans to people who have corrected their credit," said Bill Godfrey of Mason McDuffie. "It's nice to see."
The borrowers are "people who waited three years, have a job and qualify," Godfrey said. "They have their credit, have a job and things are looking better. They may not be perfect . but that's part of the way to move forward. Clearly there is some thawing in that area."
Some listing agents complain FHA loans take a lot more time and work. "It's a hard transaction to complete," said Bob Barrie of Keller Williams in San Jose, Calif. Barrie said he is listing a home next week in Santa Clara, Calif., and if there are multiple offers, a buyer with an FHA loan will be at a disadvantage.
The Davis' journey from foreclosure to new home began in 2005, when they bought a condo in Concord, Calif., for $262,000 at the peak of the market.
The couple's interest-only, 100 percent-financed loan was a classic bubble product that became a formula for foreclosure during the housing crash.
To make things worse, the condo was in a rough neighborhood, said Stacy Davis, who is a high school special-education teacher in Fremont, Calif. Her husband is a senior producer for the Golden State Warriors basketball team.
They tried to sell the condo after their daughter was born, but no one wanted to buy it, Stacy Davis said. "We decided we're going to try to stick this out. We owned it, and we would make it work."
So they remodeled, put in a new kitchen and molding. Meanwhile, the neighborhood deteriorated. Shopping carts piled up on the sidewalk, she said. Graffiti blossomed on walls.
After their son was born, they tried a short sale and found a buyer. "Within a week, an upstairs bathroom pipe busted open and flooded the whole place - the new kitchen, the molding, all destroyed. So the buyer backed out," she said. Their condo in ruins, they moved to a rented house in Dublin, Calif., and the bank foreclosed. Their credit rating dropped to about 500, but they were able to build it back to about 700.
"Within a year we were getting credit card applications. We didn't feel like it affected our lives at all," she said.
The purchase of the house in Livermore completed, the Davis family will move in early November
The Federal Housing Administration insures home loans so banks can be more flexible in making loans with lower down payments and more flexible income requirements. The FHA, which is self-supporting, was created in 1934 during the depths of the Great Depression to try to revive the housing market.
Here's what the FHA says about loans after foreclosures and short sales:
-Previous mortgage foreclosure: Borrowers are generally not eligible for a new FHA-insured mortgage if, during the previous three years, their previous principal residence or other real property was foreclosed, or they gave a deed-in-lieu of foreclosure.
Exception: The lender may grant an exception to the three-year requirement if the foreclosure was the result of documented extenuating circumstances that were beyond the control of the borrower, such as a serious illness or death of a wage earner, and the borrower has re-established good credit since the foreclosure.
Divorce is not considered an extenuating circumstance. An exception may, however, be granted where a borrower's loan was current at the time of the divorce, the ex-spouse received the property, and the loan was later foreclosed.
The inability to sell the property due to a job transfer or relocation to another area does not qualify as an extenuating circumstance.
-Borrower current at the time of short sale: A borrower is considered eligible for a new FHA-insured mortgage if, from the date of loan application for the new mortgage, all mortgage payments on the prior mortgage were made within the month due for the 12-month period preceding the short sale, and installment debt payments for the same time period were also made within the month due.
-Borrower in default at the time of short sale: A borrower in default on a mortgage at the time of the short sale (or pre-foreclosure sale) is not eligible for a new FHA-insured mortgage for three years from the date of the pre-foreclosure sale.
Exception: A lender may make an exception to this rule for a borrower in default on a mortgage at the time of the short sale if the default was due to circumstances beyond the borrower's control, such as the death of a primary wage earner or long-term uninsured illness, and if a review of the credit report indicates satisfactory credit before the circumstances beyond the borrower's control that caused the default.
On a short sale, long-term job loss or layoff would be considered an exception considered to be circumstances beyond the borrower's control.
Note: Borrowers are not eligible for a new FHA-insured mortgage if they pursued a short-sale agreement on their principal residence simply to take advantage of declining market conditions to purchase a similar or superior property within a reasonable commuting distance at a reduced price, as compared with current market value.
SOURCE: Federal Housing Administration
Monday, September 17, 2012
Bits and Pieces
2011 was the second year in a row that Orange County, CA property values are up by 2%. This is great news since with assessed values being up, so are property assessments.
Today is the last day to file an appeal on your property tax assessment. If you disagree with the assessed value, homeowners can file an Application for a Changed Assessment.
Home sales in July 2012 are up 25.7% over July 2011 and the median price of an Orange County home in July 2012 increased to $450,000.
California ranks 10th among the 50 states in terms of the amount of residential property tax residents pay. While residents rank 6th nationally in regard to their overall tax burden. The median annual residential property tax bill is $2,839. And, the average amount Californians pay per capita in state and local taxes is $4,910.
According to Zillow, combining Los Angeles and Orange County areas, buying a home beats renting in fewer than five years. Zillow's analysis looked at more than 200 metropolitan areas and 7,500 cities and in almost every instance, buying was better, but the break-even point differed. For instance, in the Riverside - San Bernardino area buying beat renting in two years while in San Francisco it took as long as 24.3 years for purchasing to pay off.
Monday, August 13, 2012
What Really Do Appraisers Look At In Determining Value?
By Alison Rogers
Money – Thu, Aug 9, 2012 1:28 PM EDT
________________________________________
When it comes to assessing a home's value, real estate agents and homeowners tend to be an optimistic bunch.
In the post-bust world, appraisers are a different story. They have to predict a realistic value for your home that the bank can use to extend credit to a borrower -- and that number can make or break your sale or refinance.
Appraisers say the following five areas are where homeowners often misjudge the worth of their abode.
1. The outside
The appraiser sees: Overgrown bushes and chipped paint.
What he does: Slices as much as 3% off the value of an average-size home.
Why: Curb appeal is primo. And an unkempt yard is a sign that there may be other issues.
"A good-looking lawn and bushes imply that you also take care of the internal systems in the house," says Jonathan Miller, president and CEO of a New York City-based appraisal firm that works throughout the tri-state area.
Moreover, the more meticulous your neighbors are about grooming, the more your appraiser will downgrade the value of your home.
"If a lot of the nearby properties are professionally maintained, the one that sticks out like a sore thumb will get a harder adjustment than in a subdivision where there's more variation," says San Diego appraiser Armando Ortiz.
2. Basic systems
The appraiser sees: A brand-new roof.
What he does: Nothing.
Why: Just as a knee replacement won't make you look 20 years younger, a new roof, furnace, or boiler isn't considered an improvement to your home.
That said, if your roof is in disrepair, replace it: Signs of leaks or discoloration can knock a significant amount off the home's value.
"When people buy a home, they expect the roof to be working," says Columbus appraiser Mike Armentrout. "So while a new one isn't an added feature, it will help your chances of a sale."
3. The basement
The appraiser sees: A recently finished basement with a half bath.
What he does: Adds about 2% to the value of the home.
Why: Yes, your finished basement adds value -- but don't expect it to count like first-floor space.
The addition of a bedroom and quarter bath on the ground floor could increase your home's value by up to 20%, especially if you've got only one other bathroom.
"A below-ground basement normally isn't included in the square footage of the house," says Miller.
The same rule applies to outbuildings like a pool-house casita, painting shed, or studio.
4. The market
The appraiser hears: Two nearby homes just went into contract above their asking prices.
What he does: Nothing.
Why: While a broker might pump up a home's asking price based on the sense that the market is "hot," by and large, appraisers are bound by the data of recent comparable sales.
What if prices are suddenly up in your area, and you're nervous that your house won't appraise for contract price? In that case, you might want to delay your appraisal until one of those recently contracted sales closes.
5. A remodel
The appraiser sees: An expensive, custom-made, built-in entertainment center.
What he does: Makes a negative adjustment to the valuation.
Why: "Cost doesn't equal value," says Miller.
Renovations that are at all trendy -- or not in keeping with the historical period of the home -- will be assessed at the cost of ripping them out.
Timeless improvements, on the other hand, such as a deep sink or new wooden cabinets in the kitchen, will add value.
So if you're thinking of remodeling, ask a local real estate agent to tell you what's on the wish list of today's buyers.
State Responsibility Area (SRA) Bills To Come Out Soon
Property owners within the State Responsibility Area (SRA) will soon be receiving a bill requiring payment up to $150 per habitable structure for state fire prevention services.
In July of 2011, the Governor signed legislation (ABX1 29) requiring affected property owners to pay a fee for state fire prevention services in their area. The fee is applied to all habitable structures within the SRA.
The SRA is the area of the state where the State of California is financially responsible for the prevention and suppression of wildfires. SRA does not include lands within city boundaries or in federal ownership. To see if your property is within the SRA, use the State Responsibility Area Viewer website:
http://www.firepreventionfee.org/sraviewer.php
The fee is levied at the rate of $150 per habitable structure, which is defined as a building that can be occupied for residential use. Owners of habitable structures who are also within the boundaries of a local fire protection agency will receive a reduction of $35 per habitable structure.
This fee will fund a variety of important fire prevention services within the SRA including brush clearance and activities to improve forest health so the forest can better withstand wildfire.
Wednesday, May 23, 2012
Ability to Purchase After A Short Sale: Update
Now that several years have passed since many of the first short sales have been consummated, many homeowners, who went through a short sale desire to get back into a home and take advantage of the great buying opportunity which exists right now.
Every day lenders receive requests from both agents and their clients to determine the eligibility to purchase again. The most often stated re-approval terms, if late mortgage payments existed at time of sale, are a 2 year wait when financing conventional with 20% down and a 4 year wait with 10% down. It is a 3 year wait with FHA which is 3.5% down. As it turns out, it is not that cut and dry like we all thought.
As we work through individual case files we have uncovered a serious defect to the system that is causing havoc to the process. Credit reporting with the bureaus does not truly reflect the terms of the escrow the seller really went through. Here is what I mean and the actual guidelines from Fannie Mae are posted below for you to examine.
A short sale is known by Fannie Mae as a pre-foreclosure in all of their guides. DU is Desktop Underwriter which is the proprietary underwriting system of Fannie Mae. In order to sell a loan to Fannie Mae the case file of the borrower must be entered into DU in order to receive a finding of an “accept” or approval. A “refer” means there is a problem.
Now, here is the real issue. When the short sale lender reports to the credit bureaus that a short sale has taken place, the bureaus report it as a pre-foreclose, an 8 or 9 to the seller’s credit files. When we run the credit years later and then run a DU, we are receiving “refers” because the system says it is a foreclosure and not eligible to have an approval as the waiting period should be 7 years, the waiting period for a foreclosure.
We contact the bureaus and say we have paperwork that shows the previous bank’s written authorization for a short sale as well as a HUD closing statement to back our claim. The credit bureaus will not change the information in their systems because…..a short sale is a pre-foreclosure which is a form of….foreclosure.
As you will see below, Fannie Mae guidelines state the lenders must manually apply the pre-foreclosure sale requirements. Perfect a solution. No it’s not. Why? Because the investors will not buy the loans unless there is a “DU ACCEPT!”
Pre-foreclosure Sales or Short Sales
• DU is not able to identify pre-foreclosure or short sales in the credit report data. Lenders must manually apply the pre-foreclosure sale requirements to DU loan case files, regardless of the underwriting recommendation received from DU.
• DU will issue a message on loan case files where the borrower's credit report indicates an account may have been released to a pre-foreclosure sale. The recommendation on the loan case file will not be changed when this information appears on the credit report, though as stated above, the lender must ensure the loan complies with all other requirements specific to pre-foreclosure sales as specified in B3-5.3-07, Significant Derogatory Credit Events — Waiting Periods and Reestablishing Credit..
DU applies the following guidelines to prior foreclosures:
• Mortgage accounts, including first liens, second liens, home improvement loans, HELOCs, and mobile home loans, will be identified as a foreclosure if there is a current status or manner of payment/MOP code of “8” (foreclosure) or “9” (collection or charge-off).
This issue is just now coming to light and as I suspect, will grow large enough creating awareness to Fannie Mae to adapt new procedures so new potential homebuyers are not shut out improperly. Personally, I intend to elevate this as much as possible and as frequently as possible to help keep it on the radar.
My advice to all is to make sure any person wanting to purchase again after going through a short sale, get fully approved through DU prior to writing any offers to purchase a home.
Foreclosure Stats
The number of new foreclosure filings fell below 200,000 for only the second time in more than four years. California was responsible for more than half of the latest improvement. Meanwhile, Boston saw a major increase in new filings.
Residential loan servicers filed foreclosure notices on 188,780 properties during April. Filings include default notices, scheduled auctions and repossessions. The last time foreclosures were this low was in July 2007, when 179,599 U.S. properties were hit with a filing.
A month earlier, filings were made on 198,853 properties, according to RealtyTrac, which provided the report based on data from 2,200 U.S. counties. The total was 219,258 a year earlier. Year-to-date foreclosure filings totaled 761,708, though some properties might have faced filings in more than one month.
More than half of last month's improvement was out of California, where the total tumbled to 39,008 from March's 45,122. Still, the Golden State had more foreclosures than any other state.
"Rising foreclosure activity in many state and local markets in April was masked at the national level by sizable decreases in hard-hit foreclosure states like California, Arizona and Nevada," RealtyTrac Chief Executive Officer Brandon Moore said in the report. "Those three states, and several other non-judicial foreclosure states like them, more efficiently processed foreclosures last year, resulting in fewer catch-up foreclosures this year."
Moore abandoned his usual warnings that suggest a foreclosure tsunami is ahead. Among the 20 biggest metropolitan statistical areas, Phoenix saw a 23 percent decline from March, the biggest improvement of any city. At the other end of the spectrum was Boston, where filings skyrocketed 47 percent.
One foreclosure was filed in April for each 698 U.S. housing units. The rate was better than one-in-662 the prior month and one-in-593 in the same month the prior year. With a foreclosure filed on each 300 housing units, Nevada grabbed the title of the state with the worst foreclosure rate.
At one-in-351, California had the second-worst rate -- though the rate improved from one-in-303 a month earlier. The Golden State was home to the Riverside-San Bernardino MSA, where the one-in-213 foreclosure rate was the worst among major MSAs. The next-worst state was Florida, with a one-in-364 rate, then Arizona's one-in-377 rate and Georgia's one-in-398 rate. The trio was home to the MSAs with the next-worst rates: Miami's one-in-273, Atlanta's one-in-298 and Phoenix's one-in-313. Tampa's one-in-315 rate was the fifth-worst of any area.
Tuesday, May 1, 2012
Interesting Statistics...FYI
I came across some interesting statistics on the economy and homeownership in particular. In January 2012 the average mortgage interest rate was 3.9%, which is an awesome rate. The interesting part of this statistic is that according to the 2012 UCLA Anderson Forecast, the expected average mortgage interest rate is expected to be 7.3% within two years. If that is not a motivating factor to try to jump into this housing market, I don't know what is. This change in interest rate will be gradual, but what that does to your monthly payment would be to increase it by $1,000 per month. This is based on the current median sales price. I don't know too many people that can handle an increase of $1,000 per month to their overhead over the course of two years. By purchasing at today's lower interest rates with the reduced prices of homes, that would amount to a savings of $345,000 over the course of a thirty-year fixed-rate loan.
Friday, March 16, 2012
Mortgage Insurance Premiums Are No Longer Tax Deductible
The ability of homeowners to write off the premiums they pay for mortgage insurance expired very quietly at the end of December 2011, along with 58 other tax code benefits that Congress failed to renew. Estimates are that this loss could cost individual homeowners between $600 and $1,000 on their annual federal income tax bills starting in 2012.
Senate Bill 332
Under Senate Bill 332 landlords of residential properties may ban the smoking of tobacco products as of January 1, 2012. Landlords have the authority to put restrictions in new leases specifying the areas on their property where smoking is prohibited.
If a lease was signed before January 1st and the landlord now wants to ban smoking, it would be a chnage in the terms of the lease. In a month-to-month tenancy, 30 days' written notice is required. In longer term tenancy, the parties will need to enter into a new agreement when the existing agreement expires or they must modify the existing agreement. For the modification to be enforceable, the landlord will need to provide some sort of consideration to the tenant in exchange for the loss of smoking privileges.
Tuesday, March 13, 2012
Mello-Roos Special Tax Assessments Will Not Be an Allowed Tax Deduction in 2012
Many California taxpayers who have been using the total amount of their property tax bill as a deduction for state income tax purposes will have to discontinue this practice with their 2012 tax bill (taxes due April 2013). Although the law hasn't changed, the Franchise Tax Board's (FTB)software has been updated. I don't think most people really understood that special assessments and user fees including things such as vector control and water district charges were never suppose to be deducted.
With a new computer system the FTB will be able to differentiate between these charges. Many of the smaller fees are rather insignificant and for many total less than $20. But the special assessments called Mello-Roos taxes are also no longer deductible, and that could make a big difference in a lot of state income tax payments. For many people in Orange County, the Mello-Roos component of their property tax bill can be close to 40%. Over 20% of the county's residents pay a Mello-Roos assessment and for the 2011-2012 tax year that amounted to about $207.8 million.
Friday, March 9, 2012
A HIDDEN FEE IS SET TO RISE...
From The New York Times
By VICKIE ELMER
Published: March 1, 2012
INSIDE the interest rate quoted on your home mortgage lies a small hidden fee that has been charged by government-sponsored entities like Fannie Mae and Freddie Mac for more than three decades. It’s an add-on rate known as the guarantee fee.
An increase in the fee has been mandated by Congress to occur this spring, and other increases are likely later this year and next. When they happen, interest rates on single-family mortgages resold to Fannie Mae or Freddie Mac are likely to inch up as well.
“It’s going to be silently passed through” by lenders when it does increase, said Richard W. Grohmann, a real estate lawyer in Paramus, N.J.
The G-fee — as it is known — does not show up in borrowers’ mortgage documents or good-faith estimates, and it is little known outside the industry.
“It gets incorporated into the underlying rate that the borrower pays,” said Andrew Wilson, a spokesman for Fannie Mae.
An interest rate is usually made up of three parts: the largest goes to the bank or the investors who buy the loan; a smaller portion is for the mortgage servicer that collects monthly payments; and then there’s the guarantee fee. Fannie and Freddie charge guarantee fees as a form of insurance against default for the loans they acquire and resell to investors.
The G-fee will rise 10 basis points on April 1; the increase was included in the two-month extension of the payroll tax reduction last December. (A basis point is equal to one one-hundredth of 1 percent, or 0.01 percent.)
Keith T. Gumbinger, a vice president of HSH Associates, a financial publisher in Pompton Plains, N.J., says the increase in the guarantee fee will very likely push up mortgage rates on new loans by one-eighth of a percentage point. “While it is most common to build the G-fee into the loan’s rate, it doesn’t have to be done that way,” he said in an e-mail, noting that some lenders might charge a flat fee instead.
Already, though, loans with interest-rate locks from the last 45 or 60 days have the higher guarantee fee written into them, according to Tom Kelly, the president of Investors Home Mortgage, a division of Investors Bank in Short Hills, N.J. Lenders say they need the extra lead time because it may take time to close the loan, package it and send it on to Fannie or Freddie.
One way to avoid the guarantee fee is to use a lender that does not sell off its loans — for instance, a community bank or a credit union.
Besides offsetting risks, the fees provide a primary source of revenue for Fannie Mae and Freddie Mac. Fannie, for instance, made $5.6 billion in single-family guarantee-fee income in the first nine months of 2011, a 4.7 percent increase from the 2010 period, according to its quarterly financial statements.
Fannie and Freddie have collected G-fees since the introduction of mortgage-backed securities in the early 1980s. “It was variable from the start, based on the volume level of loans” made by the lender, Mr. Kelly said.
Both organizations started raising fee rates in 2008 during the housing crisis, as foreclosure costs rose. G-fees gained modestly in 2010, and also last year.
New single-family loans acquired by Fannie Mae were charged a guarantee fee of 31.1 basis points, on average, in the third quarter of 2011, the most recent period for which data are available. That is six points higher than in the third quarter of 2010. Rates on multifamily loans are 15 to 20 basis points higher than on single-families.
“We expect that single-family guarantee fees will increase in the coming years,” Fannie Mae said in its third-quarter report to investors, “although we do not know the timing, form or extent of these increases.”
In a letter to Congress last month, Edward J. DeMarco, the acting director of the Federal Housing Finance Agency, which oversees Fannie Mae and Freddie Mac, suggested “continued gradual increases.”
Subscribe to:
Posts (Atom)
